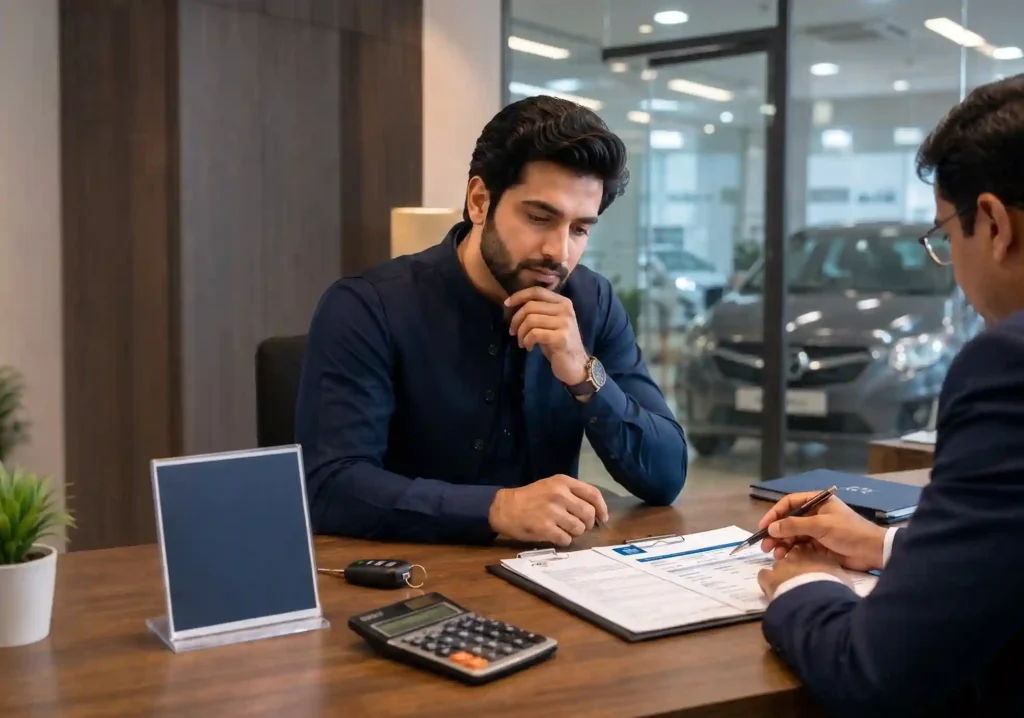

Buying a car should be exciting, but the process can quickly become confusing when a salesperson starts discussing monthly payments, financing options, and extra fees. Many buyers focus on finding a payment that fits their budget without realizing that the total price of the vehicle matters just as much.
One question deserves special attention: “How much do you want to pay per month?”
There’s nothing inherently wrong with a dealer asking this. However, answering with a specific amount before negotiating the car’s price can make it easier to structure a deal around your budget rather than the best overall price.
The good news is that you don’t need to be an expert negotiator to protect yourself. A few simple questions and a clear buying strategy can help you understand what you’re actually paying for.
1. Why the Monthly Payment Question Matters
Imagine walking into a dealership to buy a car. The salesperson asks how much you can afford each month, and you say $400.
Instead of first negotiating the vehicle’s price, the conversation may shift toward finding a loan that produces a payment close to $400. That could involve extending the loan term, increasing the down payment, or adding other costs to the financing.
You might leave believing you got a good deal because the payment fits your budget. But without examining the total price, interest rate, and loan length, you cannot know whether the deal is genuinely competitive.
The Federal Trade Commission recommends obtaining the vehicle’s out-the-door price in writing and comparing the full cost rather than focusing only on monthly payments.
2. What You Should Say Instead
You don’t need to refuse to discuss your finances. Simply keep the conversation focused on the vehicle’s price first.
If the salesperson asks, “What monthly payment are you looking for?” you could respond:
“I’d like to agree on the vehicle’s total out-the-door price first. Once we have that number, I’ll compare the financing options and decide what payment works for me.”
This response is polite, clear, and practical. It tells the salesperson that you’re interested in buying but intend to understand the complete deal before making a commitment.
It also helps separate two different decisions: how much the car costs and how you will pay for it.
3. Always Negotiate the Total Price First
The out-the-door price is the total amount required to purchase the vehicle before financing costs. It generally includes the agreed vehicle price, applicable taxes, title and registration charges, and dealer fees.
Getting this figure in writing makes it easier to compare offers from different dealerships.
For example, one dealer might advertise a vehicle at $28,000 but add several fees before you sign. Another might offer the same model for $28,500 with fewer additional charges.
The advertised price alone doesn’t tell you which deal is better. The complete written price gives you a more useful comparison.
Ask each dealer for the same information, including any optional products or accessories. That way, you’re comparing similar offers rather than relying on an attractive headline price.
4. A Lower Monthly Payment Doesn’t Always Mean a Better Deal
A smaller monthly payment can be helpful, especially when you’re managing a household budget. But it doesn’t automatically mean you’re paying less for the car.
Consider a simplified example involving a $25,000 loan at a fixed annual interest rate of 6%, assuming monthly payments and no additional fees:
| Loan term | Approximate monthly payment | Approximate total interest |
|---|---|---|
| 36 months | $761 | $2,405 |
| 48 months | $587 | $3,150 |
| 60 months | $483 | $3,980 |
| 72 months | $414 | $4,800 |
These are illustrative estimates, not a quote for a particular vehicle or lender.
Notice how the monthly payment falls as the loan term increases. However, the borrower pays substantially more interest over the longer term.
A dealer may be able to reduce the monthly payment by extending the loan, but that doesn’t necessarily reduce the overall cost. Always compare the loan term and total repayment amount before deciding.
5. Get Your Financing Options Before Visiting
One of the simplest ways to become a more confident car buyer is to research financing before entering the dealership.
Contact a bank, credit union, or other reputable lender to see whether you qualify for pre-approved financing. Ask for the annual percentage rate, loan term, estimated payment, and total amount you can borrow.
A pre-approval gives you a reference point when evaluating the dealer’s financing offer.
For example, if your bank offers a lower APR than the dealership, you can ask whether the dealer can provide a more competitive rate. You don’t have to accept the first financing option presented to you.
Compare the complete terms rather than assuming that the lowest advertised monthly payment is the best choice.
6. Watch Out for Long Loan Terms
Longer loans can make expensive vehicles appear more affordable because the payments are spread across more months.
However, a long loan can increase the total interest paid and create another problem: you may owe more on the car than it is worth.
This situation is known as negative equity.
Suppose you still owe $22,000 on a vehicle that could currently sell for $18,000. You have $4,000 in negative equity. If you trade the car in, that difference may need to be paid separately or incorporated into another loan, depending on the deal.
Rolling an old balance into a new loan can make the next purchase more expensive. Before agreeing to a trade-in, ask the dealer for the vehicle’s value and the exact amount needed to pay off your existing loan.
7. Ask for Every Fee in Writing
The vehicle’s price is only one part of the purchase agreement. Dealers may also offer optional products and services, including extended warranties, service contracts, paint protection, wheel protection, and GAP coverage.
Some products may be useful in particular circumstances, but you should understand what each one costs and whether you actually want it.
Ask the salesperson to list every proposed fee and add-on separately. If something is described as mandatory, ask why and request an explanation in writing.
Do not assume that an optional product is necessary simply because it appears on the paperwork. Review the terms, coverage limitations, and total cost before deciding.
The FTC advises consumers that optional add-ons are not automatically required and that buyers should check their contracts for products they did not agree to purchase.
8. Keep the Trade-In Separate From the New Car Price
If you’re trading in your current vehicle, avoid letting the trade-in discussion obscure the price of the car you want to purchase.
First, ask for the new vehicle’s out-the-door price. Then request a separate written offer for your trade-in.
This approach makes it easier to evaluate both sides of the transaction.
For example, a dealership might offer a generous trade-in allowance but also charge more for the replacement vehicle. Another dealer might offer a lower trade-in amount but a better price on the car you’re buying.
The only way to compare these offers fairly is to look at the individual figures and the final amount you’ll need to pay.
You should also research your current vehicle’s approximate market value before accepting a trade-in offer.
9. Read the Contract Before You Sign
Once you’ve agreed on a price and financing arrangement, don’t rush through the paperwork.
Check that the contract reflects the vehicle, price, down payment, interest rate, loan term, and payment schedule you agreed to. Review all fees and optional products carefully.
Ask for an explanation of any unfamiliar charge. If a salesperson says the contract is merely a formality, remember that the written agreement is what you need to understand before committing.
If the financing is not fully approved, ask whether the deal is final and what happens if the lender changes the terms. Don’t rely on verbal assurances when the paperwork says something different.
Take your time. A legitimate purchase should allow you to understand what you’re signing.
Pro Tip
Before visiting a dealership, write down three numbers:
- Target purchase price: The total price you hope to negotiate.
- Maximum budget: The most you can responsibly spend without putting other financial priorities at risk.
- Financing limit: The amount you can borrow and comfortably repay after considering interest and other ownership expenses.
Remember to budget for insurance, fuel, routine maintenance, registration, and unexpected repairs—not just the loan payment.
Having these numbers ready can help you stay focused when a salesperson presents a different vehicle, a longer loan term, or an attractive monthly payment.
Myth vs. Fact
| Myth | Fact |
|---|---|
| A low monthly payment means you got a good deal. | You must also consider the vehicle price, APR, loan term, and total amount repaid. |
| You should never discuss your budget with a salesperson. | You can discuss your budget, but negotiate the vehicle’s price and understand the financing before committing. |
| Dealer add-ons are always required. | Many add-ons are optional. Ask what each product costs and whether you need it. |
| A longer loan is always the more affordable option. | It may lower monthly payments but increase total interest and the risk of negative equity. |
| You must accept the dealership’s financing. | You can compare the dealer’s offer with financing from other lenders. |
Quick Checklist Before Buying a Car
Before signing a purchase agreement, make sure you can answer these questions:
- Do I have the total out-the-door price in writing?
- Have I compared the vehicle’s price with other offers?
- Do I know the APR and the full loan term?
- Have I calculated the total amount I’ll repay?
- Are all dealer fees and optional add-ons clearly listed?
- Have I researched my trade-in’s approximate value?
- Does the written contract match the deal I agreed to?
- Can I comfortably afford insurance, maintenance, fuel, and repairs in addition to the payment?
If any important figure is unclear, ask for clarification before signing.
Frequently Asked Questions
1. Should I tell a car dealer my monthly budget?
You can share your budget if you wish, but you don’t have to give a specific monthly payment before negotiating the vehicle’s price. A useful approach is to agree on the total price first and then compare financing options.
2. What is an out-the-door price?
It is the total price required to purchase the vehicle, including the agreed vehicle price and applicable taxes and fees. Ask for a written breakdown so you can identify additional charges and compare offers accurately.
3. Can I negotiate the interest rate on a car loan?
In many cases, you can ask the dealer to offer better financing terms. Comparing offers from banks, credit unions, and other lenders can give you a useful reference point. The rate available to you depends on factors such as your credit profile, lender, and loan terms.
4. Are car dealership add-ons mandatory?
Many products, such as extended warranties and paint protection, are optional. Ask the dealer to explain any item described as mandatory, review the contract, and make sure you understand which products you are agreeing to buy.
5. Is it better to pay cash or finance a car?
It depends on your finances, the vehicle’s price, the available interest rate, and what else you could do with your money. Paying cash avoids loan interest, while financing allows you to spread payments over time but adds borrowing costs. Compare the complete costs before deciding.
6. What should I do if the dealer pressures me to sign?
Ask for time to review the paperwork and request a copy of the proposed agreement. If the dealer won’t clearly explain the terms or the written price differs from what you agreed to, consider walking away and comparing another offer.
Conclusion
The question “How much do you want to pay per month?” isn’t automatically a red flag. The problem arises when the conversation focuses on a payment amount before you’ve established the vehicle’s total price and understood the financing.
A lower payment can hide a longer loan, additional interest, or extra products. By negotiating the out-the-door price, comparing financing offers, reviewing add-ons, and checking the contract, you can make a much more informed decision.
You don’t need to argue with the salesperson or refuse every offer. You simply need to understand the complete deal before agreeing to it.
Key Takeaway
Don’t judge a car deal by its monthly payment alone. Negotiate the total price first, compare the financing terms, and read every charge before signing. A few careful questions can help you avoid an expensive mistake and choose a car that genuinely fits your budget.